We are solely in the business of improving the lives of others.

Building sincere connections and progressive solutions, creates wow-experiences for our clients - fuelling their happiness and setting the stage for generational success.
GET STARTED

Finding the best mortgage can be frustrating. It doesn't have to be when you follow my 3 step plan.

Get started right away

The best place to start is to connect with me directly. My commitment is to listen to your needs, assess your financial situation, provide professional mortgage advice, and guide you through the mortgage process.

Get clarity

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let me cut through the noise. I'll outline the best mortgage products available with your needs in mind.

Proceed with confidence

My goal is to make sure you know exactly where you stand at all times. From your initial application through your mortgage renewal, I'm available to answer any questions for as long as you need a mortgage. I've got you covered.
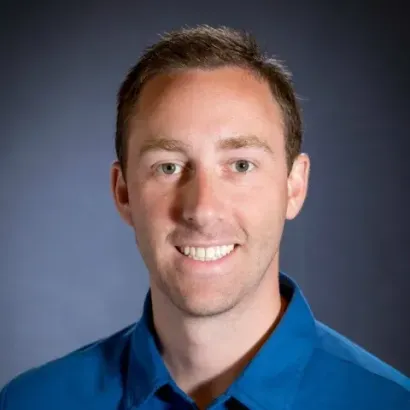
Chad Oyhenart

Thanks for visiting my page, I'm Chad, a licensed mortgage broker focused on providing my clients with an amazing service experience. I specialize in educating my clients on the topics of home buying, refinancing, and explaining in plain english the process of getting a mortgage.


I work closely with other industry professionals that include a realtor, notary, and financial advisor - all who provide the same approach to educational service so that you can feel confident in every aspect of your decision making process. When you work with me, you will see that my process is very team oriented and we make sure you're looked after every step of the way.  


I pride my service on taking the worry and angst out of home buying for all my clients.


So if you're looking to buy your first home, or to refinance or renew an existing mortgage, you're looking to consolidate some debt, or just purchase your next home, you've come to the right place! Why don't you get in touch, we'll talk through a pre-approval, and you'll be well on your way! 

Nice things people have said about working with us.

Get started by completing an online mortgage application.

APPLY NOW

We'll let you know exactly where you stand so you can proceed with confidence.

Let's run some numbers

Start by telling us where you're at in your home buying journey.
Everything you need, all in one place

As a trusted mortgage providers, let us help you with these services.

Click through any of the services to learn more
Mortgage articles to keep you informed.

By Chad Oyhenart • October 15, 2026
Thinking of Calling Your Bank for a Mortgage? Read This First. If you're buying a home or renewing your mortgage, your first instinct might be to call your bank. It's familiar. It's easy. But it might also cost you more than you realize—in money, flexibility, and long-term satisfaction. Before you sign anything, here are four things your bank won’t tell you—and four reasons why working with an independent mortgage professional is the smarter move. 1. Your Bank Offers Limited Mortgage Options Banks can only offer what they sell. So if your financial situation doesn’t fit neatly into their guidelines—or if you’re looking for competitive terms—you might be out of luck. Working with a mortgage broker? You get access to mortgage products from hundreds of lenders : major banks, credit unions, monoline lenders, alternative lenders, B lenders, and even private funds. That means more options, more flexibility, and a much better chance of finding a mortgage that fits you. 2. Bank Reps Are Salespeople—Not Mortgage Strategists Let’s be honest: most bank mortgage reps are trained to sell their employer’s products—not to analyze your financial goals or tailor a long-term mortgage plan. Their job is to generate revenue for the bank. Independent mortgage professionals are different. We’re not tied to one lender—we’re tied to you. Our job is to shop around, negotiate on your behalf, and recommend the mortgage that offers the best balance of rate, terms, and flexibility. And yes, we get paid by the lender—but only after we find you a mortgage that works for your situation. That creates a win-win-win: you get the best deal, we earn our fee, and the lender earns your business. 3. Banks Don’t Lead with Their Best Rate It’s true. Banks often reserve their best rates for those who ask for them—or threaten to walk. And guess what? Most people don’t. Over 50% of Canadians accept the first renewal offer they get by mail. No questions asked. That’s exactly what the banks count on. Mortgage professionals don’t play that game. We start by finding lenders offering competitive rates upfront, and we handle the negotiations for you. There’s no guesswork, no pressure, and no settling for less than you deserve. 4. Bank Mortgages Are Often More Restrictive Than You Think Not all mortgages are created equal. Some come with hidden traps—especially around penalties. Ever heard of a sky-high prepayment charge when someone breaks their mortgage early? That’s often due to something called an Interest Rate Differential (IRD) —and big banks are notorious for using the harshest IRD calculations. When we help you choose a mortgage, we don’t just focus on the interest rate. We look at the whole picture, including: Prepayment privileges Penalty calculations Portability Future flexibility That way, if your life changes, your mortgage won’t become a financial anchor. A Quick Recap What your bank typically offers: Only their own limited mortgage products Sales-focused representatives, not mortgage strategists Default rates that aren’t usually their best Restrictive contracts with high penalties What an independent mortgage professional delivers: Access to over 200 lenders and customized mortgage solutions Personalized advice and long-term financial strategy Competitive rates and terms upfront Transparent, flexible mortgage options designed around your needs Let’s Talk Before You Sign Your mortgage is likely the biggest financial commitment you’ll ever make. So why settle for a one-size-fits-all solution? If you're buying, refinancing, or renewing, I’d love to help you explore your options, explain the fine print, and find a mortgage that truly works for you. Let’s start with a conversation—no pressure, just good advice.
By Chad Oyhenart • October 1, 2026
Owning a vacation home or an investment rental property is a dream for many Canadians. Whether it’s a cottage on the lake for family getaways or a rental unit to generate extra income, real estate can be both a lifestyle choice and a smart financial move. But before you dive in, it’s important to know what lenders look for when financing these types of properties. 1. Down Payment Requirements The biggest difference between buying a primary residence and a vacation or rental property is the down payment. Vacation property (owner-occupied, seasonal, or secondary home): Typically requires at least 5–10% down, depending on the lender and whether the property is winterized and accessible year-round. Rental property: Usually requires a minimum of 20% down. This is because rental income can fluctuate, and lenders want extra security before approving financing. 2. Property Type & Location Not all properties qualify for traditional mortgage financing. Lenders consider: Accessibility : Is the property accessible year-round (roads maintained, utilities available)? Condition : Seasonal or non-winterized cottages may not meet standard lending criteria. Zoning & Use : If it’s a rental, lenders want to ensure it complies with municipal bylaws and zoning regulations. Properties that fall outside these norms may require financing through alternative lenders, often with higher rates but more flexibility. 3. Rental Income Considerations If you’re buying a property with the intent to rent it out, lenders may factor the rental income into your mortgage application. Long-term rentals : Lenders typically accept 50–80% of the expected rental income when calculating your debt-service ratios. Short-term rentals (Airbnb, VRBO, etc.) : Many traditional lenders are cautious about using projected income from short-term rentals. Alternative lenders may be more flexible, depending on the property’s location and your financial profile. 4. Debt-Service Ratios Lenders use your Gross Debt Service (GDS) and Total Debt Service (TDS) ratios to determine if you can handle the mortgage payments alongside your other obligations. With investment or vacation properties, lenders may apply stricter guidelines, especially if your primary residence already carries a large mortgage. 5. Credit & Financial Stability Your credit score, employment history, and overall financial health still matter. Since vacation and rental properties are considered higher risk, lenders want reassurance that you can handle the additional debt—even if rental income fluctuates or the property sits vacant. 6. Insurance Requirements Rental properties often require specialized landlord insurance, and vacation homes may need coverage tailored to seasonal or secondary use. Lenders will want proof of adequate insurance before releasing mortgage funds. The Bottom Line Buying a vacation property or rental can be exciting, but financing these purchases comes with extra rules and considerations. From higher down payments to stricter property requirements, lenders want to be confident that you can handle the responsibility. If you’re considering a second property, the best step is to work with a mortgage professional who can compare lender requirements, outline your options, and find the financing that works best for you. Thinking about making your dream of a vacation or rental property a reality? Connect with us today.
By Chad Oyhenart • September 17, 2026
Owning a home feels great—carrying a large mortgage, not so much. The good news? With the right strategies, you can shorten your amortization, save thousands in interest, and become mortgage-free sooner than you think. Here are four proven ways to make it happen: 1. Switch to Accelerated Payments One of the simplest ways to reduce your mortgage faster is by moving from monthly payments to accelerated bi-weekly payments . Instead of 12 monthly payments a year, you’ll make 26 half-payments. That works out to the equivalent of one extra monthly payment each year, shaving years off your mortgage—often without you noticing much difference in your budget. 2. Increase Your Regular Payments Most mortgages allow you to boost your regular payment by 10–25%. Some even let you double up payments occasionally. Every extra dollar goes directly toward your principal, which means less interest and faster progress toward paying off your balance. 3. Make Lump-Sum Payments Depending on your lender, you may be able to make lump-sum payments of 10–25% of your original mortgage balance each year. This option is ideal if you receive a bonus, inheritance, or other windfall. Applying a lump sum directly to your principal immediately reduces the interest charged for the rest of your term. 4. Review Your Mortgage Annually It’s easy to put your mortgage on auto-pilot, but a yearly review keeps you in control. By sitting down with an independent mortgage professional, you can check if refinancing, restructuring, or adjusting terms could save you money. A quick annual review helps ensure your mortgage is always working for you—not against you. The Bottom Line Paying off your mortgage early doesn’t require a massive lifestyle change—it’s about making smart, consistent choices. Whether it’s accelerated payments, lump sums, or regular reviews, every step you take helps reduce your debt faster. If you’d like to explore strategies tailored to your situation—or want a free annual mortgage review—let’s connect. I’d be happy to help you find the fastest path to mortgage freedom.